The 52-Week Saving Challenge: A Simple Path to $1,378
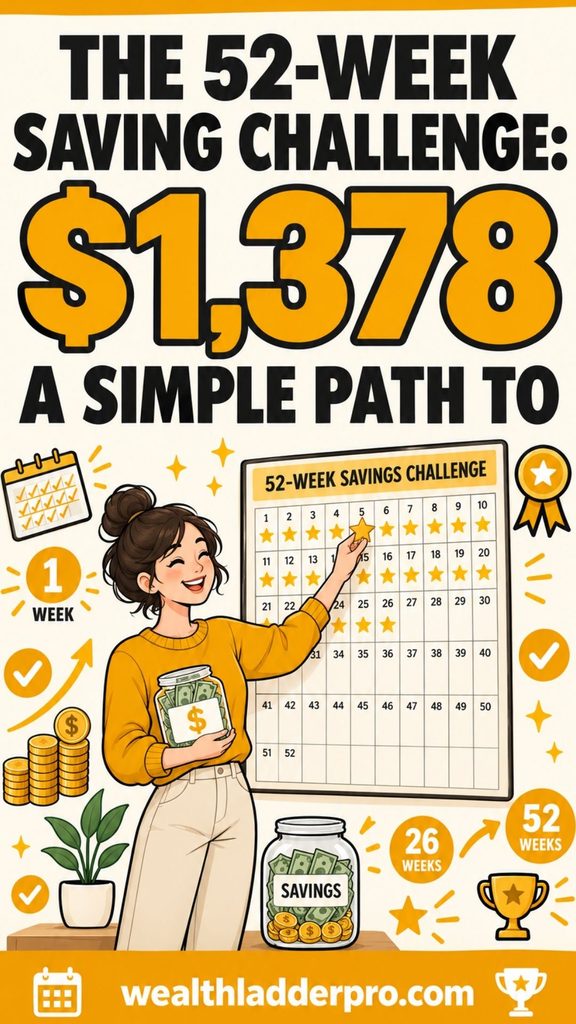
The 52-Week Saving Challenge is a savings method where you deposit an increasing amount each week for a year, starting at $1 in week one and adding $1 more each week until you save $52 in week 52.
By year’s end, you’ll have banked $1,378 without ever having to set aside a large lump sum at once.
Saving money feels harder than ever right now. Eighty percent of Americans say they haven’t grown their emergency savings at all since the start of 2024, and about a third have actually watched their savings shrink over the same period, according to Bankrate’s Emergency Savings Report. If you’re in that group, you’re far from alone.
That’s exactly why the 52-Week Saving Challenge has stuck around as one of the most popular ways to rebuild a financial cushion.
It doesn’t ask you to slash your budget overnight or find hundreds of extra dollars each month.
Instead, it works with small, incremental deposits that grow week by week until they add up to something substantial.
The premise is refreshingly simple: start with $1 in week one, increase your deposit by $1 every week, and finish week 52 having saved $1,378.
This post covers exactly how the challenge works, why it’s effective, practical tips for sticking with it, variations to match different budgets, common obstacles you might hit along the way, and a real-life example of how it plays out.
How the 52-Week Saving Challenge Works
The mechanics of the 52-Week Saving Challenge are straightforward. Each week, you save an amount that matches the week number.
In week 1, you set aside $1. In week 2, you save $2. This pattern continues, climbing steadily until week 52, when you deposit $52.
Here’s a snapshot of how the totals build over time, based on Bankrate’s breakdown:
| Week Number | Weekly Deposit | Total Savings |
|---|---|---|
| Week 1 | $1 | $1 |
| Week 10 | $10 | $55 |
| Week 25 | $25 | $325 |
| Week 50 | $50 | $1,275 |
| Week 52 | $52 | $1,378 |
The math behind it is elegantly simple: the sum of every number from 1 to 52 equals $1,378. There’s no complicated formula to memorize, just a steady, upward climb.
One of the best things about the 52-Week Saving Challenge is its flexibility around timing.
While many people kick it off in January as a New Year’s resolution, there’s no rule saying you have to wait. You can start this week, next month, or any time you decide you’re ready to build better savings habits.
Why the 52-Week Saving Challenge Works: Key Benefits
The appeal of this challenge goes beyond just the final dollar amount. Several psychological and practical factors make it genuinely effective for building savings goals.
It builds savings discipline gradually. Rather than treating saving as an occasional chore, the weekly rhythm turns it into a habit.
Small, repeated actions are easier to sustain than sporadic big pushes.
It sets an achievable starting point. A dollar is easy to find, even on a tight budget.
This low barrier to entry removes the intimidation factor that often stops people from saving in the first place.
It creates visible motivation through progress. Watching your running total climb week after week delivers a small hit of accomplishment that keeps you engaged.
That $1,378 milestone starts to feel within reach much sooner than you’d expect.
It serves as a stepping stone toward bigger savings goals. Whether you’re building an emergency fund, saving for a vacation, or starting a down payment fund, this challenge offers a structured on-ramp.
This structure matters more than it might seem. According to Raisin, 51% of Americans have less than three months of emergency savings, and 25% have none at all.
For anyone in that position, the 52-Week Saving Challenge offers an accessible, low-pressure way to start closing that gap.
Practical Tips for Staying Committed
Starting the challenge is easy. Staying consistent through all 52 weeks takes a bit more strategy. These money management tips can help.
Automate your transfers. Set up a recurring transfer to a high-yield savings account so you’re not relying on memory or willpower each week. Once it’s automated, the challenge runs largely on its own.
Track your progress visually. Whether it’s a printable checklist, a spreadsheet, or a savings app, seeing each completed week marked off makes the challenge feel tangible and satisfying.
Celebrate milestones along the way. Reward yourself every 13 weeks, roughly quarterly, to reinforce your progress and keep motivation high through the full year.
Bring in an accountability partner. Invite a friend or family member to join you and check in monthly. Shared goals tend to stick better than solo ones.
Choose the right account for your savings. A high-yield savings account not only earns interest on your growing balance, it also creates a small barrier against impulse withdrawals, since the money isn’t sitting in your everyday checking account.
Also Read: How to Make Money On Snapchat: 10 Proven Ways to Earn Real Income
Variations to Fit Your Budget and Lifestyle
The standard version of the 52-Week Saving Challenge isn’t the only option. Several variations exist to better match different budgets and savings goals.
Reverse challenge: Start at $52 in week one and decrease by $1 each week. This front-loads your larger deposits when your budget may have more room, easing the pressure during the higher-spending holiday season.
Constant amount challenge: Skip the increasing structure entirely and save a flat $26.50 every week. You’ll reach the same $1,378 total, and the consistent amount makes automation even simpler.
Double-up challenge: Start at $2 in week one and increase by $2 weekly. This more ambitious version totals $2,756 by year’s end, ideal for those with bigger savings goals and more flexibility in their budget.
Triple-up challenge: Start at $3 and increase by $3 each week, finishing the year with $4,134 saved.
The specific structure matters far less than consistency. Pick the version that realistically fits your income and goals, since the challenge only works if you can sustain it for the full 52 weeks.
Common Obstacles (and How to Overcome Them)
Even with the best intentions, most people hit a few bumps during the year. Here’s how to handle the most common ones.
Missed weeks: Life happens. If you fall behind, catch up with a lump sum when you can, or use a windfall like a tax refund or work bonus to close the gap.
Unexpected expenses: Build some flexibility into your plan. If money’s tight one week, it’s better to pause the challenge temporarily than to abandon it altogether.
Motivation dips: This is where the earlier tips pay off. Lean on your visual tracker, your quarterly rewards, and your accountability partner to push through the slower stretches.
Holiday spending crunch: If December’s expenses always throw off your savings, the reverse challenge variation solves this problem directly by scaling down your deposits as the year winds on.
Real-Life Success Stories
Plenty of people have used the 52-Week Saving Challenge to hit meaningful savings goals.
One popular example shared in online personal finance communities describes a saver who not only completed the standard challenge but modified it to save even more, ultimately setting aside tens of thousands of dollars in a single year by adapting the structure to fit larger paycheck contributions.
For illustration, consider a composite example based on common experiences: Sarah, a hypothetical saver starting the challenge in January, admitted the first few months felt almost too easy.
By the summer, when her weekly deposits climbed past $30, she leaned on an accountability partner to stay on track.
By December, she’d hit her full $1,378, using it to cover a portion of an unexpected car repair without touching her existing emergency fund.
Her key takeaway: the challenge worked less because of the dollar amount and more because it built a consistent savings reflex she didn’t have before.
Also Read: Emergency Fund Savings: The Number That Changes Everything
Start Your Own 52-Week Savings Journey
The 52-Week Saving Challenge offers something rare in personal finance advice: a plan that’s genuinely simple to follow and delivers a real result.
Save $1,378 over a year, one manageable deposit at a time, without ever needing to make a dramatic financial sacrifice.
The real value here isn’t only the dollar figure. It’s the habit you build along the way, and the financial confidence that comes from proving to yourself that consistent saving is achievable.
Pick the variation that fits your budget, whether that’s the standard climb, the reverse structure, or a flat weekly deposit, and start this week rather than waiting for a new year or a “better time.”
Consider downloading a savings tracker to keep yourself accountable, or explore our related budgeting guides for more ways to strengthen your financial habits.
52 Week Saving Challenge Calculator
This calculator helps you stay on track with a step-by-step plan to save $1,378 in just one year.
It breaks the goal into manageable weekly amounts, making saving simple and less overwhelming.
Each week, you’ll deposit an amount that gradually increases, starting small and building up as you go.
The calculator adjusts to your pace, whether you want to stick to the classic weekly increase, swap the order for a reverse plan, or keep it consistent with fixed deposits.
It’s your practical tool for turning a big goal into smaller, achievable steps that fit your budget and lifestyle.
52 Week Saving Challenge Kenya
The 52 Week Saving Challenge is a simple, step-by-step way to save $1,378 over a year by breaking it down into small, manageable amounts each week.
You’ll start with just $1 in the first week, then increase your savings by an extra dollar weekly—$2 in week two, $3 in week three, and so on.
By the final week, you’re saving $52, and the total adds up faster than you’d expect. This approach makes saving feel achievable, even on a tight budget, and gives you a clear plan to follow.
Whether you stick to the classic order, reverse it to save more earlier, or adjust for fixed amounts, it’s a flexible way to meet your goals while staying consistent.
Also Read: From $0 to Secure: Emergency Fund Basics That Actually Work
52 Week Saving Challenge Safaricom
The 52-week saving challenge with Safaricom is a practical way to save $1,378 in a year by starting small and building up gradually.
You begin by saving just $1 in the first week, then increase the amount by $1 each week—$2 in week two, $3 in week three—until week 52, where you save $52.
This step-by-step approach keeps things manageable and motivates you to stay consistent.
You can adjust it to your preference, like saving larger amounts earlier if you want quicker results.
It’s simple, flexible, and a great way to form a steady savings habit while working toward a clear financial goal.
52 Week Money Challenge Savings Plan
The 52-week saving challenge is a smart, step-by-step way to save $1,378 in a year by starting small and building up weekly.
You begin with just $1 in the first week, then add $1 more to your savings each week—so week two is $2, week three is $3, and so on.
By the final week, you’re saving $52, and it all adds up without feeling overwhelming.
This approach is simple to follow, keeps you motivated with visible progress, and can be adjusted to fit your budget or goals.
It’s an easy, flexible way to develop consistent saving habits and work toward something meaningful, whether a big purchase or an emergency fund.
Frequently Asked Questions
How much do you save in a 52-week challenge?
The standard 52-Week Saving Challenge totals $1,378 by the end of the year.
This comes from saving an amount matching each week number, starting at $1 in week one and ending at $52 in week 52.
What is the reverse 52-week challenge?
The reverse 52-week challenge flips the standard structure. Instead of starting small and increasing, you start at $52 in week one and decrease by $1 each week.
This front-loads larger deposits earlier in the year, which can help offset higher spending during the holiday season.
Can I start the 52-Week Saving Challenge at any time of year?
Yes.
While many savers begin in January as part of a New Year’s resolution, the 52-Week Saving Challenge can start any week of the year.
What matters most is committing to the full 52-week cycle once you begin.
What happens if I miss a week during the challenge?
Missing a week doesn’t mean you have to abandon the challenge.
Catch up with a lump-sum deposit when possible, or apply a windfall like a tax refund or bonus to get back on track.
Which savings account should I use for this challenge?
A high-yield savings account is generally recommended.
It allows your deposits to earn interest over the year and creates a small barrier against impulse withdrawals, compared to keeping the money in an easily accessible checking account.