From $0 to Secure: Emergency Fund Basics That Actually Work
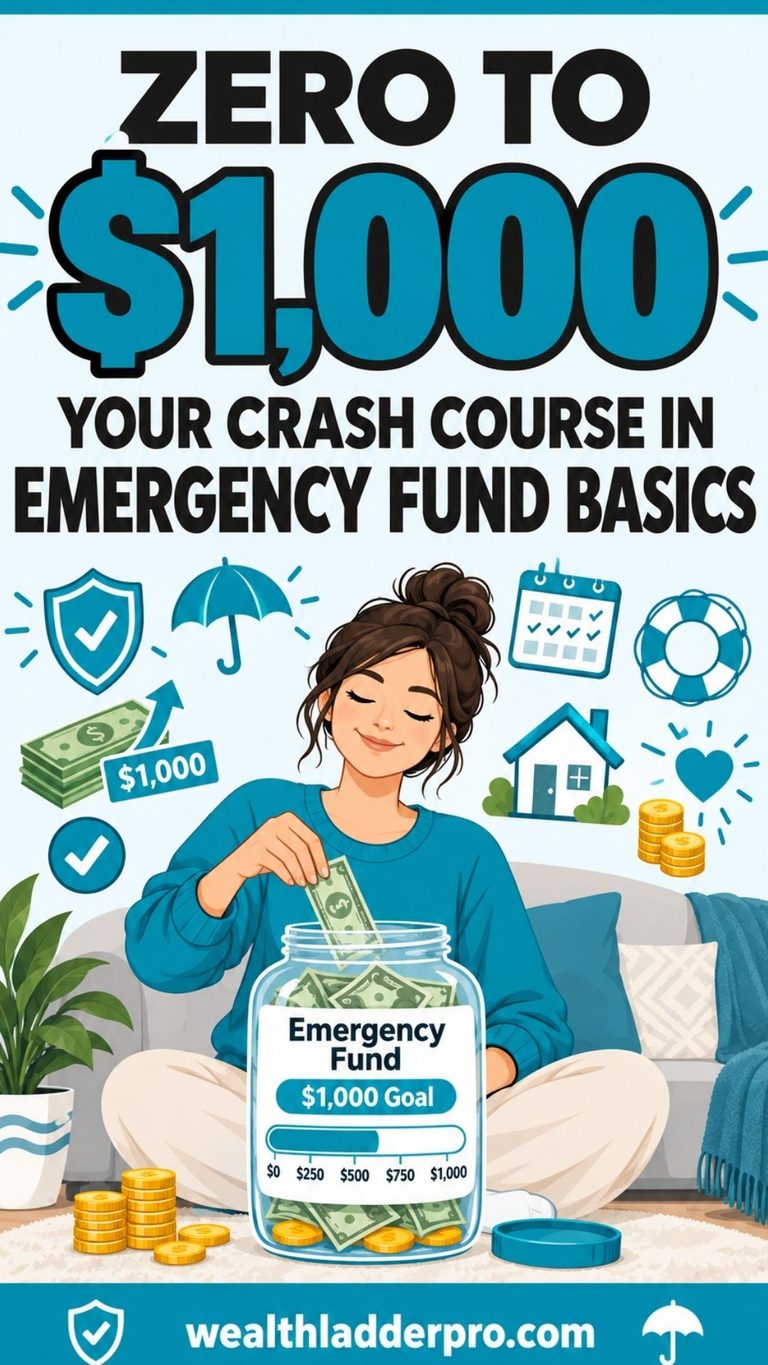
Building an emergency fund starts with a small, realistic goal—like $1,000—followed by automated weekly contributions into a high-yield savings account.
Aim for 3-6 months of essential expenses over time, track your progress, and avoid non-emergency withdrawals. Consistency matters more than the size of your paycheck.
Nearly a third of Americans have no emergency savings at all, and many others have far less than they’d need to cover even a minor setback (Bankrate, 2025; Federal Reserve).
That gap leaves millions of households one car repair or medical bill away from real financial trouble.
Emergency fund basics aren’t complicated, but they do require intention. Whether your income is modest or comfortable, financial security planning starts with the same foundational habit: setting aside money you won’t touch unless something genuinely unexpected happens.
This post walks through exactly how to build savings account reserves from scratch, step by step, even if you’re starting with a $0 balance today.
You don’t need a six-figure salary to get there. You need a plan, a bit of patience, and the willingness to start small.
What Is an Emergency Fund (and Why It Matters)?
An emergency fund is money set aside exclusively for unexpected expenses: job loss, a medical bill, an urgent home repair, or a car that suddenly refuses to start. It’s not for vacations, holiday gifts, or a sale on something you’ve had your eye on. It exists for one purpose—keeping you financially stable when life throws a curveball.
This matters more than most people realize. According to Empower’s 2024 research, 37% of Americans couldn’t cover a surprise $400 expense without borrowing or going into debt. That’s a striking number, and it shows just how thin the margin is for a large share of households, regardless of income bracket.
It’s worth distinguishing an emergency fund from a “rainy day fund.” A rainy day fund is smaller and covers predictable surprises, like a $200 appliance repair. An emergency fund is the larger reserve meant for major disruptions, such as losing a job or a costly medical procedure.
Beyond the financial math, there’s a psychological benefit too. Over half of Americans (54%) report feeling stressed about not having enough saved. A fund isn’t just a buffer against bad luck. It’s peace of mind you can feel on a daily basis, long before you ever need to use it.
How Much Should You Actually Save?
The standard recommendation is 3-6 months of essential living expenses. That includes rent or mortgage, utilities, groceries, insurance, and minimum debt payments. It does not include discretionary spending like dining out or streaming subscriptions.
Here’s a simple formula to calculate your target:
- Add up your monthly essential expenses.
- Multiply that number by 3 for a starter goal.
- Multiply it by 6 for your full emergency fund target.
For example, if your essential expenses total $2,500 a month, your starter goal is $7,500, and your full target is $15,000.
That said, this number isn’t one-size-fits-all. Someone living in a high cost-of-living city will need a considerably larger cushion than someone in a more affordable area, since rent and everyday expenses vary so dramatically by location. If the full 3-6 month target feels overwhelming, that’s normal. Instead, start with a smaller, motivating milestone, like $1,000, before working toward the larger goal.
Start Small: Realistic Savings Goals
You don’t need to save thousands overnight. Small, consistent contributions add up faster than most people expect.
A good starting point is $25-50 per week. That translates to $1,300-$2,600 over a year, without requiring any dramatic lifestyle changes. Consider someone saving $25 a week: within a year, they’ll have built a $1,300 cushion, enough to cover many of the most common emergencies without relying on credit cards or loans.
Here’s the encouraging part: less than 15% of Americans currently budget for emergency savings at all. Simply starting, even with a modest weekly amount, puts you ahead of most of the population.
Also Read: Make Money on Quora: Your Guide to Turning Answers into Income
Automate Your Way to Consistency
Willpower is unreliable. Automation isn’t. When you set up a system that saves money before you have a chance to spend it, consistency becomes far easier to maintain.
This is a real opportunity, because only 11% of Americans currently automate their emergency savings. Most people are still relying on manual transfers, if they’re saving at all, which means good intentions frequently fall through the cracks.
Set up a recurring transfer from your checking account to a dedicated savings account, timed to hit right on payday. Start with a small, “painless” amount, even $10-20 per paycheck, and increase it gradually as the habit sticks and your budget allows.
Pick the Right Home for Your Fund
Where you keep your emergency fund matters almost as much as how much you save. High-yield savings accounts (HYSAs) are the ideal vehicle, balancing easy access with meaningful growth.
Traditional savings accounts typically offer minimal interest, often a fraction of a percent. HYSAs, by contrast, have offered rates approaching 5% APY in recent years (Bankrate, 2025). Consider this example from American Express: $10,000 sitting in an HYSA earning 4% APY generates roughly $400 a year in interest. That’s essentially free money for doing nothing more than choosing the right account.
HYSAs also carry FDIC insurance up to $250,000, making them a low-risk place to build savings account balances over time. When comparing providers, look closely at fees, current interest rates, and how easy it is to transfer funds when you actually need them.
Track Progress and Celebrate Milestones
Visualizing progress, whether through an app, a spreadsheet, or even a simple thermometer chart, keeps motivation high during the months when growth feels slow.
Celebrate the milestones along the way: your first $500, your first $1,000, and eventually one full month of expenses saved. These markers matter. Fewer than half of Americans met their savings goals in 2024, which suggests that tracking and accountability make a measurable difference between those who succeed and those who stall out.
A simple monthly check-in, reviewing what you contributed and adjusting as needed, can keep your emergency fund moving in the right direction without becoming a source of stress.
Also Read: Turn Your Skills Into Cash: A Complete Guide to Make Money on Fiverr
Protect Your Fund: Avoid Non-Emergency Withdrawals
An emergency fund only works if it stays intact when it’s not needed. That’s harder than it sounds. Notably, 21% of Americans have used their emergency savings for holiday spending, which defeats the purpose of having the fund in the first place.
Before withdrawing, apply a simple test: is this expense unexpected, necessary, and urgent? If the answer to any of those is no, it’s probably not a true emergency.
One practical safeguard is keeping your emergency fund in a separate account from your everyday spending money. This reduces temptation and creates a mental boundary between “spendable” cash and your safety net. It’s a habit that’s already common practice: 56% of Americans keep their emergency fund separate from their regular savings account.
Build Incrementally Toward the Full Goal
Reaching 3-6 months of expenses is a marathon, not a sprint. Incremental progress is still real progress, even if it takes a year or two to hit the full target.
Whenever your income rises, whether through a raise, a bonus, or a tax refund, consider directing a portion of that increase toward your emergency fund. This accelerates your progress without disrupting your current budget or lifestyle.
If you’re also carrying high-interest debt, you don’t necessarily have to choose one or the other. A balanced approach, such as building a small starter fund first and then splitting extra funds between debt repayment and savings, can keep you moving forward on both fronts simultaneously.
Review and Adjust Annually
Life changes, and so should your emergency fund target. An annual financial check-up helps you reassess the right amount as your expenses, income, or circumstances shift, whether that’s a new home, a new baby, or a job change.
Recalculate your 3-6 month target each year. Rising costs mean that last year’s goal may no longer be sufficient today. This annual review is also a good opportunity to acknowledge how far you’ve come, not just what’s left to save.
Start Building Your Safety Net Today
Building an emergency fund comes down to a handful of consistent steps: define your goal, start small, automate your contributions, choose a high-yield savings account, track your progress, protect the fund from non-emergency use, and review your target annually.
Financial security planning isn’t about perfection. It’s about consistent, incremental action, taken week after week, even when the amounts feel small. The households that succeed aren’t necessarily the ones with the highest incomes. They’re the ones who started.
Take the first step this week, even if it’s just opening a dedicated savings account. From there, everything else builds naturally.
Also Read: How to Make Money with a Laptop: Real Opportunities That Actually Pay
How Do You Build an Emergency Fund
Start small and stay consistent. Begin by setting aside any manageable amount, even just a few dollars, into a separate savings account dedicated solely to emergencies. Treat it like a bill—make regular contributions weekly or monthly, no matter how small. Look for ways to trim expenses, like cutting unnecessary subscriptions or dining out less, and redirect those savings into the fund. Any unexpected windfalls, like bonuses or tax refunds, can also give your fund a quick boost. Focus on building momentum—each deposit brings you closer to greater financial peace of mind.
How to Build an Emergency Fund Fast
Starting from scratch, focus on taking small but consistent steps to build your emergency fund quickly. Begin by setting a clear goal—decide how much you need for three to six months of essential expenses. Open a separate savings account just for emergencies, making it easier to track progress and avoid spending the money. Commit to automatic transfers, even if the amount is small, and prioritize this like any other bill. Find extra cash by cutting small expenses—like brewing your coffee at home or canceling unused subscriptions—and funnel those savings directly into your fund. Selling things you no longer need or taking on a side gig can also add to your efforts. Celebrate the progress, no matter how incremental, because every deposit builds the cushion you’ll thank yourself for later.
how long to build emergency fund
The time it takes to build an emergency fund depends on your savings goal and how much you can set aside each month. Start by calculating three to six months’ worth of essential expenses, then break it into manageable chunks. Even if you’re starting small, like setting aside $20 a week, the consistency will add up. Look for small ways to save or earn extra money to speed things up, like cutting unnecessary costs or selling unused items. Commit to regular contributions, treat it like a non-negotiable priority, and adjust as your income grows.
Frequently Asked Questions
How much should I save for an emergency fund?
Most financial experts recommend 3-6 months of essential living expenses, including rent, utilities, groceries, insurance, and minimum debt payments. Start with a smaller goal of $1,000 if the full target feels out of reach, then build from there.
How do I start an emergency fund with no money?
Begin with a small, consistent weekly contribution, such as $25, and automate the transfer so it happens without requiring ongoing decisions. Even modest amounts add up meaningfully within a year.
What’s the difference between an emergency fund and a rainy day fund?
A rainy day fund is smaller and covers predictable surprises, like a minor appliance repair. An emergency fund is a larger reserve meant for major disruptions, such as job loss or significant medical expenses.
Where should I keep my emergency fund?
A high-yield savings account (HYSA) is generally the best option, offering meaningful interest (often near 4-5% APY) while remaining easily accessible. HYSAs are also FDIC-insured up to $250,000, making them low-risk.
How do I avoid dipping into my emergency fund for non-emergencies?
Keep the fund in a separate account from your everyday spending, and apply a simple test before withdrawing: is the expense unexpected, necessary, and urgent? If not, it likely doesn’t qualify.