Stop the Cash Drain: 9 Smart Ways to Cut Monthly Expenses
To cut monthly expenses, start by tracking your spending for 30 days, then build a realistic budget using a framework like the 50/30/20 rule. From there, cancel unused subscriptions, cook more meals at home, shop smarter with generic brands, lower utility bills, negotiate recurring rates, and build an emergency fund.
Small, consistent changes across these areas compound into significant monthly savings.
The average American household spends $6,545 a month—roughly $78,535 a year—according to the Bureau of Labor Statistics’ 2024 Consumer Expenditure Survey.
That’s not pocket change. And it’s not just spending that’s climbing. The average American also carries approximately $63,500 in debt, according to USAFacts data drawn from the Federal Reserve Bank of New York.
Put those two numbers together, and it’s easy to see why so many paychecks feel like they disappear the moment they land.
Rising costs make the challenge even sharper. Between higher grocery bills, climbing rent, and everyday essentials costing more than they did a few years ago, keeping monthly expenses in check requires more than good intentions—it requires a plan.
The good news: cutting monthly expenses doesn’t mean giving up your quality of life. It means being more deliberate about where your money goes. This guide walks through nine practical, actionable strategies to help you lower monthly bills, reduce expenses, and build financial breathing room—starting with the most important step of all: knowing where your money currently goes.
Why Should You Track Your Spending Before Creating a Budget?
You can’t cut monthly expenses you haven’t identified. Tracking spending is the foundation of every successful save money tips strategy because it reveals patterns you might not notice otherwise—like the $6 coffee habit that adds up to $180 a month, or the three streaming subscriptions you forgot you signed up for.
Start simple. Use a budgeting app like Mint, YNAB, or EveryDollar, or build a basic spreadsheet if you prefer full control over your categories. The tool matters less than the consistency. Commit to logging every expense for 30 days, from your mortgage payment down to your afternoon snack run.
Once you’ve collected a month of data, compare your spending to national averages. According to the BLS, the three largest categories for the average U.S. household are:
- Housing: 33.4% of total spending ($2,189/month)
- Transportation: 17.0% of total spending ($1,110/month)
- Food: 12.9% of total spending ($847/month)
If your housing costs are eating up 45% of your budget instead of 33%, that’s a clear signal about where to focus. Seeing your numbers next to the national benchmark makes it much easier to spot where you’re overspending relative to typical households. Consider building a simple chart or infographic of your own spending by category—visualizing the breakdown makes overspending far easier to catch than scanning a spreadsheet.
What’s the Best Budget Planning Framework for Cutting Expenses?
Once you know where your money goes, it’s time for budget planning that actually holds up under real life. Two frameworks stand out for their simplicity and effectiveness:
Zero-based budgeting assigns every dollar of income a job—whether that’s rent, groceries, savings, or debt repayment—until your income minus your expenses equals zero. This method forces intentionality but requires more monthly maintenance.
The 50/30/20 rule is a lighter-touch option: 50% of income goes to needs, 30% to wants, and 20% to savings and debt repayment. It’s less precise than zero-based budgeting but easier to sustain long term.
Whichever framework you choose, start by separating fixed costs (rent, car payments, insurance premiums) from variable or discretionary costs (dining out, entertainment, shopping). Fixed costs are harder to change quickly, but variable costs are where most people find room to cut monthly expenses without much sacrifice.
Choose zero-based budgeting if you want maximum control and don’t mind revisiting your numbers weekly. Choose the 50/30/20 rule if you want a simpler system that still keeps spending in check. Either way, schedule a monthly budget review—your expenses shift over time, and your budget should shift with them.
How Much Money Do Forgotten Subscriptions Really Cost You?
Subscriptions are quiet budget killers. The average American spends around $90 a month on subscription services, and a meaningful portion of that goes toward memberships that go unused. Common culprits include:
- Streaming: Netflix, Hulu, HBO Max
- Food delivery: DoorDash, UberEats
- Music: Spotify
- Shopping memberships: Amazon Prime and similar programs
Here’s a simple action step: pull up the last three months of your bank or credit card statements and highlight every recurring charge. If you can’t remember using a service in the last 30 days, cancel it. For subscriptions you genuinely enjoy but don’t need year-round—like a seasonal streaming service for one show—consider rotating them on and off instead of paying for constant access.
This single habit is one of the fastest save money tips available, because it requires no lifestyle change—just a few minutes of review.
Also Read: Make Money on Twitch: 9 Proven Monetization Strategies for 2026
How Can Cooking at Home Instead of Dining Out Lower Monthly Bills?
According to BLS data, Americans spend an average of $519 a month on groceries (food at home) compared to $329 a month eating out (food away from home). That gap represents real opportunity.
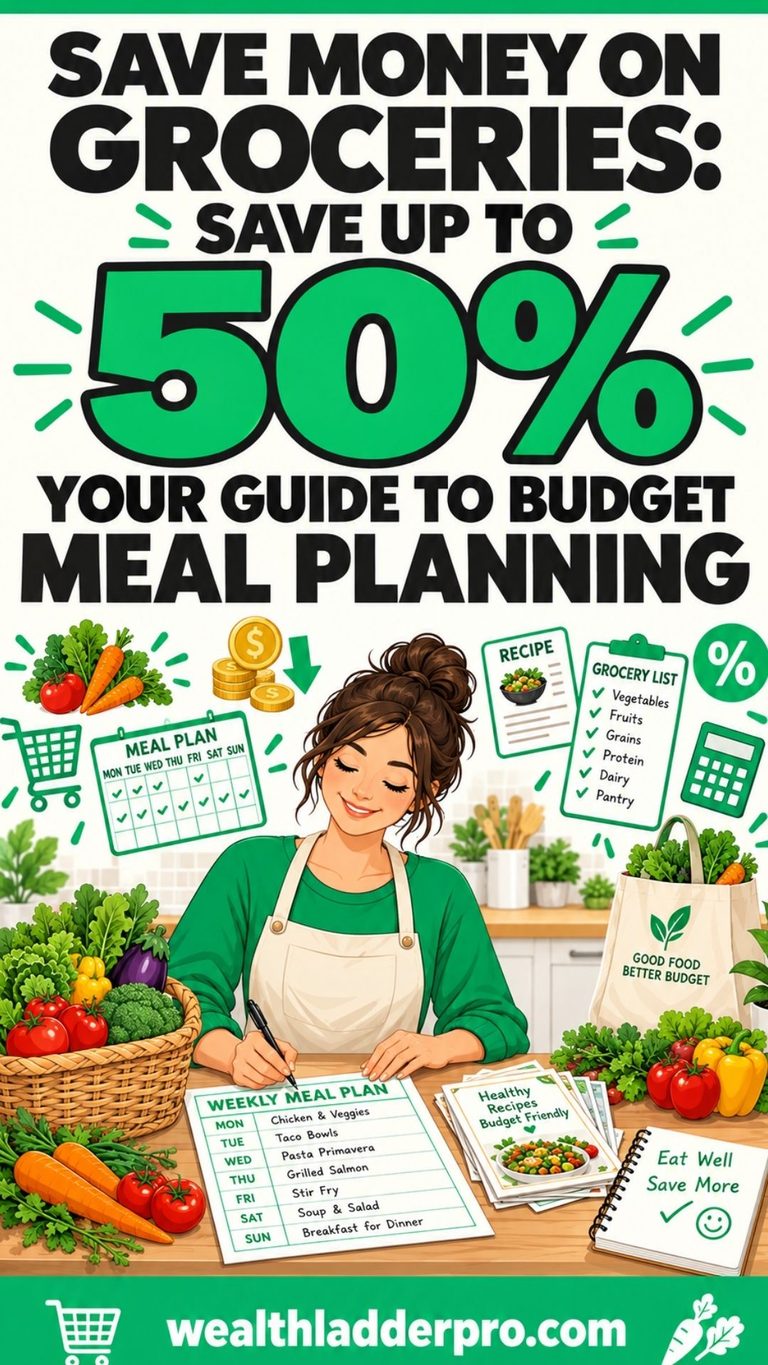
Meal planning is the key to closing it. When you plan meals in advance, you avoid the last-minute takeout order that happens simply because nothing is thawed or prepped. Try these practical tips:
- Batch cooking: Prepare large portions of staples like grains, proteins, and roasted vegetables that can be mixed into multiple meals throughout the week.
- Sunday meal prep: Spend an hour or two each weekend prepping lunches and dinners for the days ahead.
- Brew coffee at home: Swapping a daily $5 coffee shop habit for home-brewed coffee can save well over $100 a month on its own.
Here’s a relatable example: if you currently split spending evenly between groceries and dining out, cutting your dining-out budget in half could save close to $165 a month—without requiring you to give up eating out altogether.
Do Generic Brands and Coupons Really Save Money?
Yes. Switching from name-brand to generic or store-brand products can save 20% to 30% on comparable items, particularly for pantry staples, over-the-counter medications, and cleaning supplies. The quality difference is often negligible, especially for basics like flour, canned goods, and paper products.
Beyond brand-switching, a few tools can automate savings:
- Browser extensions and apps like Rakuten or Honey automatically search for discount codes and cashback offers at checkout.
- Buying non-perishables in bulk reduces the per-unit cost of items you use regularly.
- Shopping seasonal produce lowers grocery bills while often improving freshness and flavor.
Treat grocery shopping the same way you treat any other controllable, trackable expense in your budget planning process. Small percentage savings on a weekly grocery bill add up significantly over a year.
What Are the Easiest Ways to Lower Utility Bills?
Energy costs are one of the more overlooked categories when people try to cut monthly expenses, but small habit changes can add up to real savings. One family found that adjusting their thermostat by just two degrees—warmer in summer, cooler in winter—saved them between $40 and $70 a month on electricity.
Other quick wins include:
- Switching to energy-efficient LED light bulbs
- Using smart power strips to eliminate “phantom” energy draw from devices left plugged in
- Taking shorter showers to reduce water heating costs
- Running the dishwasher and washing machine only with full loads
For bigger structural savings, consider scheduling a home energy audit. Many utility companies offer these for free or at a low cost, and they can identify insulation gaps, outdated appliances, or leaks that are quietly inflating your bill. None of these changes are dramatic on their own, but consistency across a full year turns small habits into meaningful savings.
Also Read: From Zero to Portfolio: How to Trade Stocks Like a Pro
Can You Actually Negotiate Bills Like Insurance and Internet?
Many people assume their monthly bills are fixed, but insurance premiums, phone plans, and internet service are often more negotiable than they appear. Providers frequently offer retention deals or promotional rates to customers who ask—especially those threatening to switch providers.
A simple script works well: mention how long you’ve been a loyal customer, then ask directly whether there’s a lower rate available or reference a competitor’s pricing. It costs nothing to ask, and the potential savings can be substantial.
If negotiating isn’t your strength, services like BillShark or Trim will negotiate on your behalf, typically taking a percentage of whatever they save you. It’s a low-effort way to lower monthly bills without the awkward phone call.
It’s also worth reviewing insurance policies annually. Rates change, competitors introduce new offers, and loyalty doesn’t always translate into the best deal. A yearly check-in ensures you’re not quietly overpaying.
Why Is an Emergency Fund Essential for Breaking the Debt Cycle?
Remember that $63,500 average debt figure from the introduction? A lack of savings is often at the root of it. Without a cash buffer, unexpected expenses—a car repair, a medical bill, a job loss—get pushed onto credit cards, and the debt cycle begins.
Building an emergency fund doesn’t require a massive initial goal. Start small: aim for $500 to $1,000 first. Once you hit that milestone, work toward the more robust target of three to six months’ worth of expenses.
The easiest way to build this fund without relying on willpower alone is automation. Set up a small, automatic transfer into a separate savings account each payday. Even $25 or $50 a week adds up faster than most people expect, and because it happens automatically, saving stops feeling like a sacrifice.
An emergency fund isn’t just a safety net for emergencies—it’s what makes it easier to stick to your budget long term, because unexpected costs no longer derail your entire financial plan.
How Do Financial Goals Help You Stick to a Budget?
Cutting monthly expenses is far easier to sustain when it’s tied to a specific goal. “Spend less” is vague and hard to stay motivated by. “Save $3,000 for a vacation by June” or “Pay off my credit card balance by December” gives your budget planning a clear finish line.
The SMART goal framework—Specific, Measurable, Achievable, Relevant, and Time-bound—turns vague intentions into trackable targets. Instead of “save more money,” a SMART version might read: “Save $200 a month for 12 months to build a $2,400 emergency fund.”
Schedule monthly check-ins to review your progress against that goal. Are you on track? Did an unexpected expense throw things off? Adjust as needed rather than abandoning the plan altogether.
Finally, celebrate small wins along the way. Hitting the halfway mark on a savings goal, or successfully sticking to your grocery budget for two months straight, deserves recognition. Motivation fades fast without it.
Take Control of Your Monthly Budget Today
Cutting monthly expenses comes down to three consistent habits: tracking your spending, building a realistic budget, and trimming the categories that add up the fastest—housing, transportation, food, subscriptions, and utilities. None of these strategies require dramatic lifestyle changes. They require consistency.
Small changes compound. Canceling one unused subscription, cooking one extra meal at home each week, or negotiating a better rate on your internet bill might not feel significant in isolation—but stacked together over months, they add up to real financial breathing room.
You don’t need to tackle all nine strategies at once. Pick one or two that feel most doable this month, whether that’s downloading a budgeting app like YNAB or reviewing your last three bank statements for forgotten subscriptions. Momentum builds from there.
Ready to take the next step? Download a free expense tracker template or explore budgeting apps like Mint or EveryDollar to put these strategies into action right away—and subscribe for more budget planning resources and save money tips delivered straight to your inbox.
Also Read: How To Make Extra Money: Side Hustle Ideas & Passive Income That Work
How to Reduce Your Monthly Expenses
Start by tracking where your money goes each month—review your bills, subscriptions, and daily spending habits. Cancel services you no longer use, like that forgotten streaming subscription, and compare providers for essentials like insurance or internet to find better deals. Plan meals ahead to avoid costly takeout, and consider more energy-efficient options at home to cut utility costs. Small changes, like brewing coffee instead of buying it or setting spending limits on non-essentials, can add up quickly. Stay consistent, and revisit your budget monthly to keep improving.
How to Cut Your Living Expenses in Half
Start by tracking every expense to see exactly where your money is going—it’s easier to cut costs when you know the problem areas. Cancel unused subscriptions, switch to more affordable providers for essentials like internet or phone plans, and shop around for better deals on insurance. Plan your meals weekly to avoid expensive takeout, buy groceries in bulk, and stick to energy-efficient habits at home to lower your utility bills. Set clear spending limits on extras like shopping or entertainment, and choose free or low-cost alternatives for fun. With small, consistent changes, you’ll notice significant savings over time.
How to Lower My Monthly Expenses
Start by reviewing your regular bills and subscriptions, canceling anything you no longer use or need. Compare providers to find cheaper options for services like internet, phone, or insurance. Plan meals ahead to avoid impulse takeout, buy pantry staples in bulk, and cook at home more often. Be mindful of your energy use by turning off unused lights or devices and choosing energy-efficient appliances to lower utility costs. Set a clear budget for non-essentials like shopping or entertainment, and explore free or low-cost activities for leisure. Small, steady adjustments can quickly add up to noticeable savings.
How to Cut My Monthly Expenses
Start by tracking where your money goes each month to spot areas for quick adjustments. Cut down on subscriptions you rarely use and negotiate better rates for essentials like your internet or phone plan. Plan meals for the week, cook at home more often, and buy bulk pantry staples to avoid costly takeout. Save energy by unplugging unused devices and switching to energy-saving bulbs. For shopping, set a firm budget and stick to it, and try swapping expensive outings for free or affordable activities. These small, active changes can make a big difference over time.
Frequently Asked Questions
How can I cut my monthly expenses fast?
The fastest way to cut monthly expenses is to review your last three bank statements for unused subscriptions and cancel them immediately. This requires no lifestyle change and can free up $50–$100 a month within minutes. Pairing this with one dining-out reduction per week compounds the savings quickly.
What’s the easiest way to start budget planning?
The easiest way to start budget planning is with the 50/30/20 rule: allocate 50% of income to needs, 30% to wants, and 20% to savings and debt repayment. It requires less maintenance than zero-based budgeting while still creating clear spending boundaries.
How much should I have in an emergency fund before focusing on other savings goals?
Start with a smaller goal of $500 to $1,000 before working toward three to six months of expenses. This initial buffer covers most minor emergencies and prevents new debt from accumulating while you build toward the larger target.
Are budgeting apps worth using instead of a spreadsheet?
Budgeting apps like Mint, YNAB, and EveryDollar automate expense tracking and categorization, which saves time compared to manual spreadsheet entry. Choose an app if you want automatic bank syncing and reminders; choose a spreadsheet if you want full control over categories and don’t mind manual entry.
Can negotiating bills really lower my monthly expenses?
Yes. Insurance, phone, and internet providers frequently offer lower rates or retention deals to customers who ask, especially those referencing competitor pricing. Services like BillShark or Trim can also negotiate on your behalf for a percentage of the savings achieved.